
Loading
Preparing your coverage insights...
Our Locations
Loading
Preparing your coverage insights...
Cargo van insurance for couriers, expediters, and final-mile drivers: why personal auto typically excludes business use, when a for-hire van needs MC authority and the $300,000 federal filing, the coverage stack, Amazon Relay's equipment rules, and how Dragon quotes vans through Progressive Commercial.
Get a cargo van insurance quote. One call compares the carriers we write side by side.
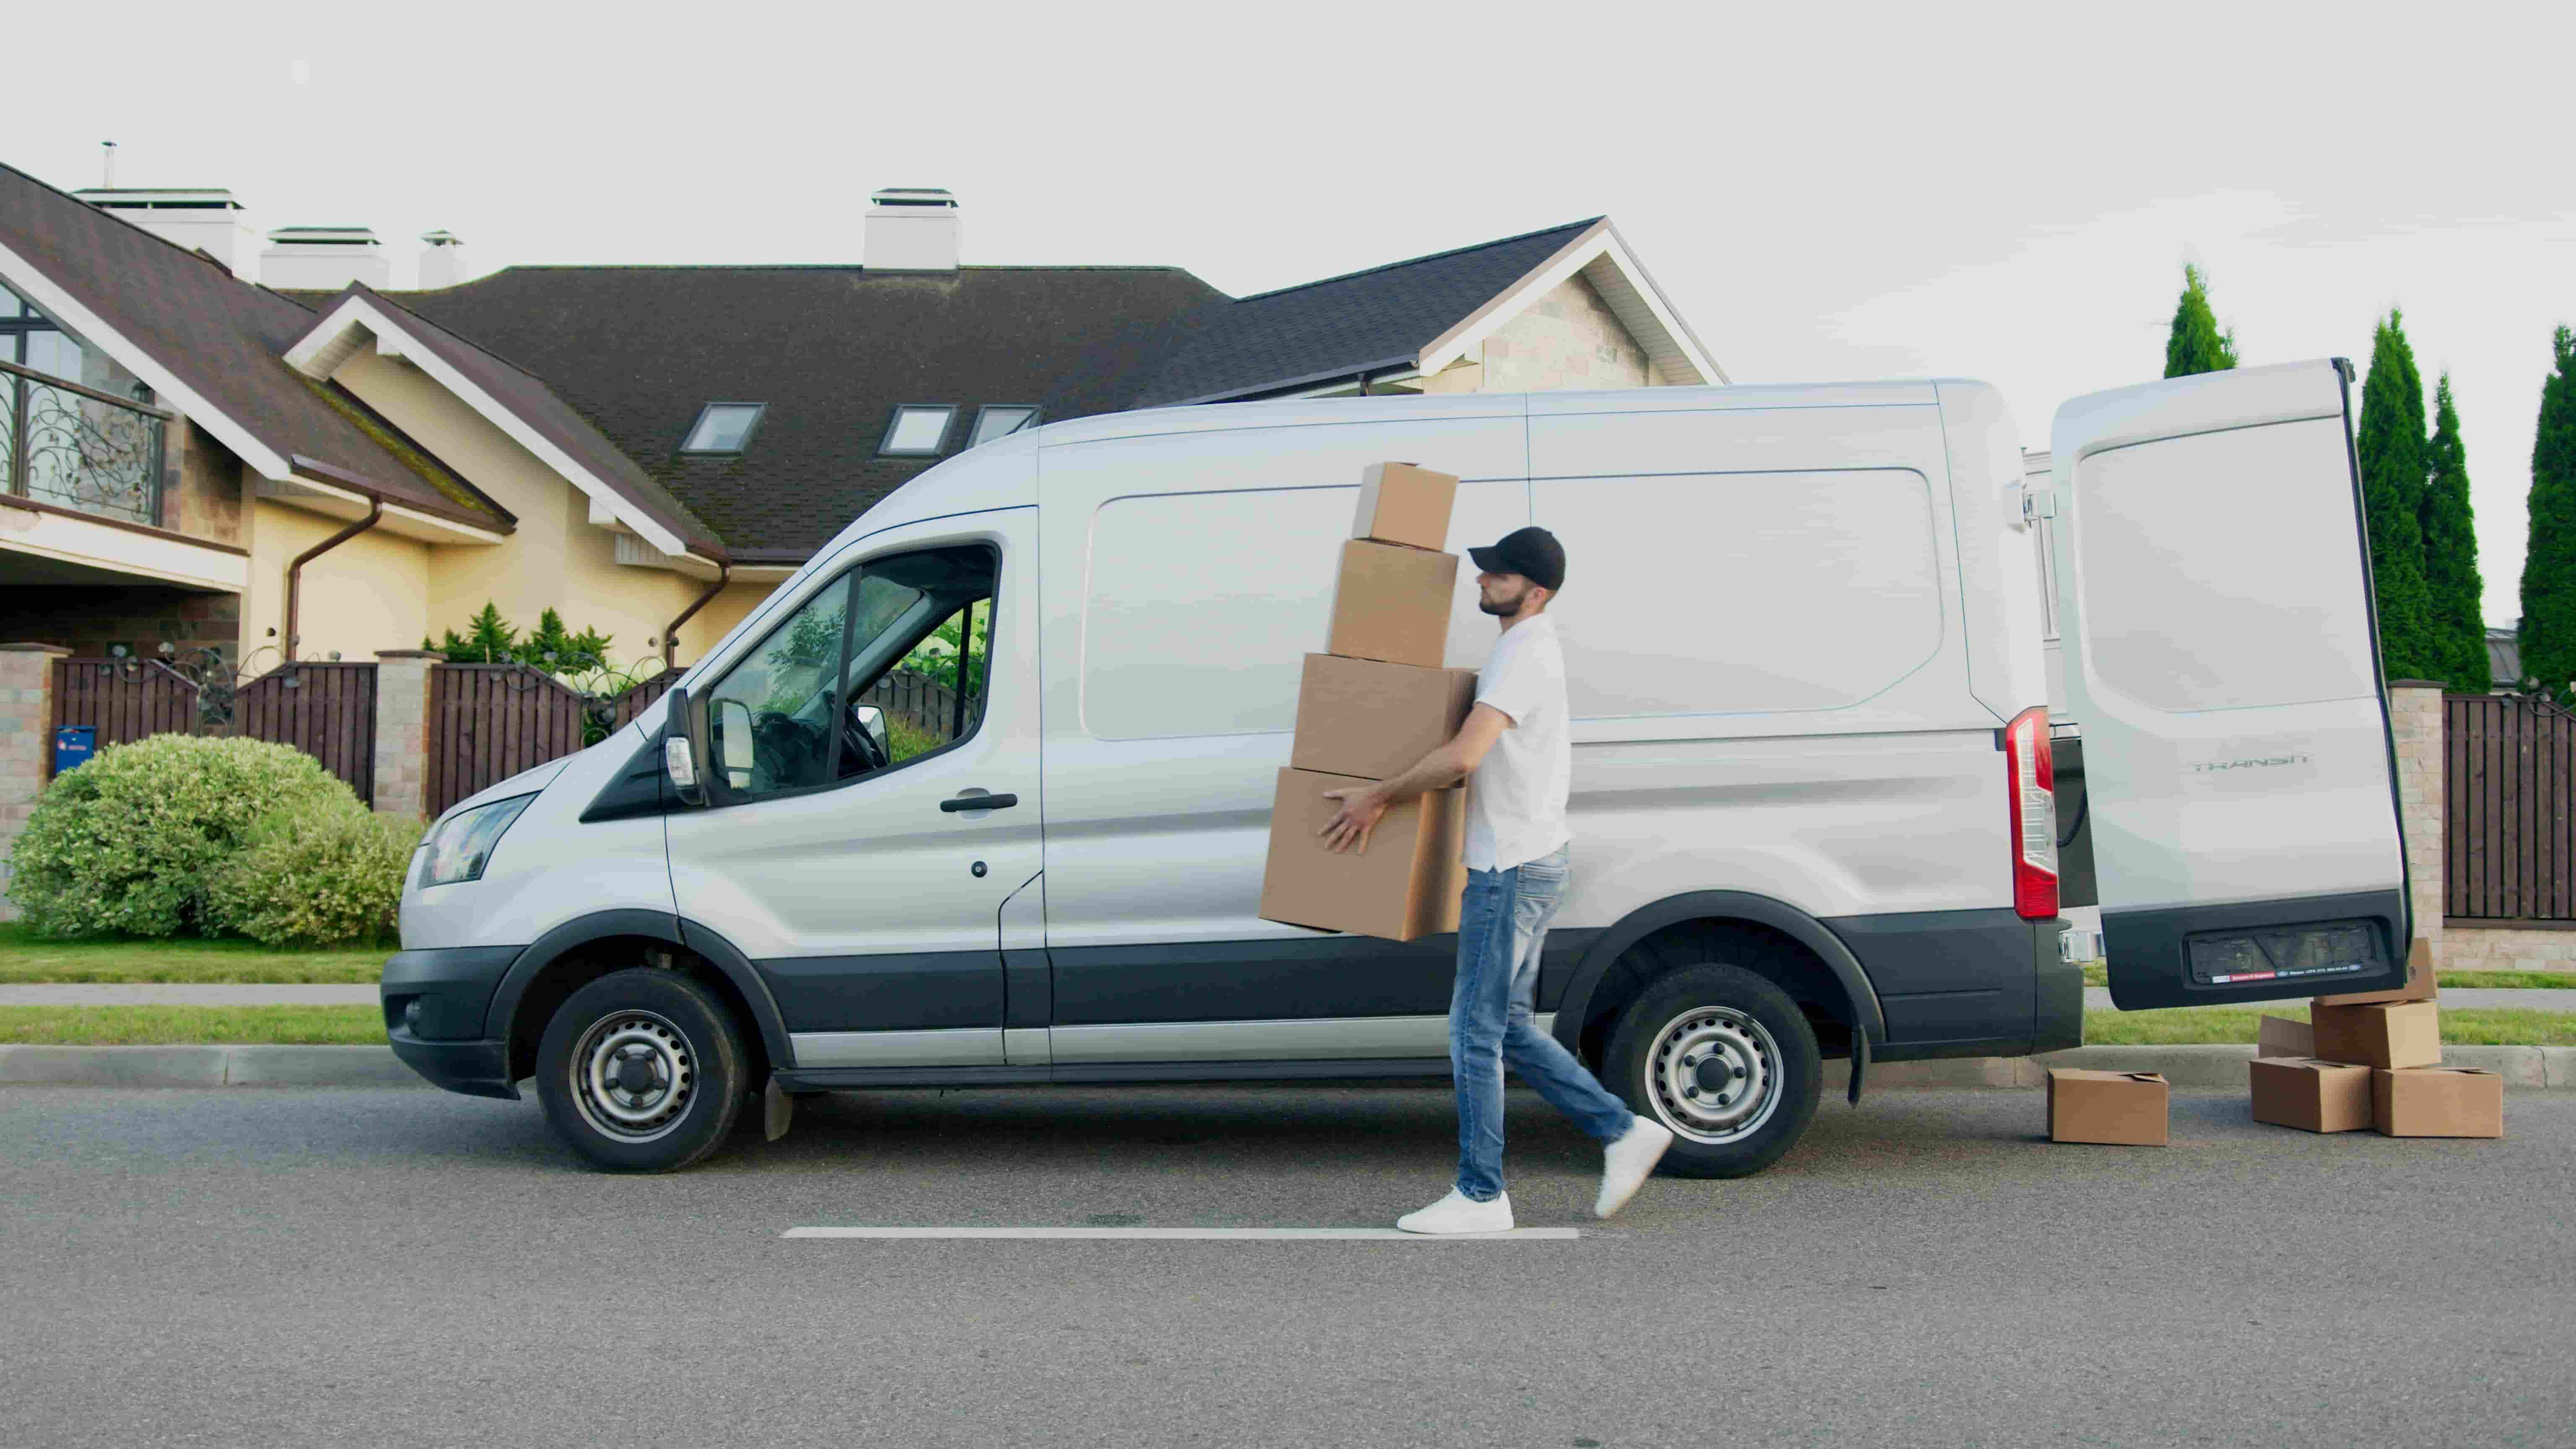
A cargo van is the cheapest way into the freight business, which is exactly why so many couriers, expediters, and final-mile drivers start with one. It is also where a lot of them get caught uninsured: a personal auto policy is not built for hauling other people's goods for pay, and a single delivery accident can land on you personally.
Dragon Insurance is an independent agency in Camp Hill, PA. We quote commercial cargo van and Sprinter van policies through Progressive Commercial, which insures cargo vans, delivery vans, and Sprinter vans for courier and delivery businesses. This guide covers what coverage a for-hire van needs, when you need MC authority, which load programs accept vans, and how to get quoted in one call.
Quick Answer
Do you need commercial insurance for a cargo van? Yes, if you use the van for courier, delivery, or expedited freight work. Personal auto policies typically do not cover business use, so a for-hire cargo or Sprinter van needs a commercial auto policy with liability, physical damage, and cargo coverage, plus a $300,000 federal liability filing if you haul for hire across state lines. Dragon quotes it through Progressive Commercial: 717-229-5115.
Key Takeaways
Cargo van insurance is commercial auto coverage for a van used in a business, including couriers, parcel and final-mile delivery, and expedited freight in Sprinter-style vans. According to Progressive Commercial, the most common commercial van coverages are liability and physical damage, with cargo, general liability, and workers' compensation added as the business needs them.
This guide is about vans that haul goods for pay. If your van carries your own tools and materials to job sites, see our commercial van insurance for contractors guide instead.
Personal auto insurance typically does not cover business use, so a claim that happens while you deliver for pay can be denied. That leaves the injury, the other driver's car, and the freight in your van on you.
If you haul other people's freight for pay across state lines, yes: FMCSA requires for-hire interstate carriers to hold operating authority (an MC number), even when the vehicle is a van. FMCSA's insurance filing requirements set the liability your insurer must file:
| Your van and your work | Federal liability minimum | What to check |
|---|---|---|
| For-hire, interstate, van rated under 10,001 lbs | $300,000 filed with FMCSA | MC authority, BOC-3, broker limits |
| For-hire, interstate, van rated 10,001 lbs or more | $750,000 filed with FMCSA | Full commercial vehicle rules apply |
| Hauling only inside one state | Set by that state | State authority, such as PA PUC in Pennsylvania |
| Hauling only your own goods (private carrier) | No federal operating authority | Commercial auto still needed for business use |
Sources: FMCSA insurance filing requirements and 49 CFR 387.9. FMCSA also exempts carriers that haul only exempt commodities or operate only within a federally designated commercial zone. Check the GVWR on your van's door-jamb label; some heavy-duty configurations are rated over 10,001 lbs.
Getting your own authority? Our guide to insurance for a new trucking authority walks through the USDOT, MC, BOC-3, and insurance filing steps in order. Hauling only inside Pennsylvania? See our Pennsylvania trucking insurance requirements for PA PUC rules.
Most cargo van businesses build their policy from four or five parts, matched to the work and the contracts they sign.
| Coverage | What it pays for | Who needs it |
|---|---|---|
| Commercial auto liability | Injuries and damage you cause to others while driving for work | Every business van; the filing for interstate for-hire work |
| Physical damage | Collision and comprehensive on your own van | Any van you would need to replace; required if financed |
| Motor truck cargo | Loss or damage to the freight you are carrying | Couriers and expediters; most brokers require it |
| General liability | Injuries and damage at pickup and delivery locations | Businesses with contracts that require it |
| Workers' compensation | Employee injuries on the job | Businesses with employees, under state law |
Not sure what cargo limit to carry? Our motor truck cargo insurance guide shows how to match the limit to your most valuable load.
Courier, expedite, or final mile?
Get your cargo van quoted on the limits your brokers actually ask for.
Tell us your van, your radius, and the freight you haul. We quote it through Progressive Commercial and handle the federal filing if you run under your own authority.
No. Amazon Relay's accepted equipment is day cab and sleeper tractors and 16-foot or 26-foot box trucks with a functional tuck-under lift-gate, so cargo vans and Sprinter vans are not on the list. Relay also requires a DOT number with interstate authority active at least 180 days and a valid MC number, plus $1,000,000 auto liability, $100,000 cargo, $1,000,000 general liability per occurrence, and workers' compensation, according to Amazon's Relay requirements.
Planning to move up to a box truck for Relay? Our box truck insurance cost guide covers 16-foot and 26-foot trucks, and we can quote the Relay limits so you are ready.
There is no set price for cargo van or courier insurance, because every business has different risks. Your quote moves with the work you do, your van's value, your limits, your location, your driving record, your deductibles, and your annual mileage. Call 717-229-5115 and we quote your van through Progressive Commercial.
Ready to compare? Get a commercial auto insurance quote for your cargo van, or call and we start your quote on the call.
Have these in front of you and we can quote your van through Progressive Commercial on the call.
Your Business and Drivers
Your Van and Contracts
Have this list in front of you. We start your quote on the call.
Call 717-229-5115Do I need commercial insurance for a cargo van?
Yes, if you use it for courier, delivery, or expedited freight work. Personal auto policies typically do not cover business use, so a claim during a paid delivery can be denied. A commercial auto policy covers liability and physical damage, and cargo coverage protects the freight you carry.
How much is cargo van insurance for a courier business?
There is no set price, because each courier business has different risks. Your quote depends on the type of work, your van's value, your limits, your location, your driving record, your deductibles, and your annual mileage. Call 717-229-5115 and we quote your van through Progressive Commercial.
Do cargo vans need MC authority?
If you haul other people's freight for pay across state lines, FMCSA requires operating authority (an MC number), even in a van. Exceptions include private carriers hauling their own goods, carriers of exempt commodities, and carriers operating only within a federally designated commercial zone.
How much insurance does a cargo van need for MC authority?
FMCSA lists a $300,000 liability filing for for-hire property carriers using vehicles under 10,001 lbs, and $750,000 at 10,001 lbs or more. Most brokers ask for $1,000,000 in liability plus a cargo limit before they will book you, so most expediters carry more than the federal minimum.
Can you do Amazon Relay with a cargo van?
No. Amazon Relay accepts tractors and 16-foot or 26-foot box trucks with a tuck-under lift-gate, and it requires interstate authority active at least 180 days plus $1,000,000 auto liability and $100,000 cargo. If Relay is your goal, plan for a box truck and quote those limits ahead of time.
What does cargo van insurance cover?
A commercial cargo van policy usually combines liability for injuries and damage you cause, physical damage on the van, and cargo coverage for the freight you haul. Many businesses add general liability for pickup and delivery locations and workers' compensation for employees.
Does hired and non-owned auto insurance cover delivery drivers using their own cars?
Hired and non-owned auto coverage generally protects your business from liability when employees use their own cars for business errands. It does not repair the employee's car, and it is not a substitute for a commercial policy on vans your business owns and uses for deliveries.
Does a Sprinter van need commercial insurance?
Yes, when it is used for courier, delivery, or expedited freight. Progressive Commercial insures Sprinter vans as commercial vans. Check the GVWR on the door-jamb label, because some heavy-duty configurations are rated over 10,001 lbs, which raises the federal liability minimum for for-hire work to $750,000.
One call, several carriers
We quote your cargo van or courier with Progressive Commercial side by side, so you see the real lowest price instead of a single company's offer.
Fast, honest quoting
Call and we start your quote on the spot. Online requests get a reply from a licensed agent within 1 hour on business days.
Your whole business in one place
General liability, commercial auto, workers comp, and tools coverage placed and serviced by one agency, with one renewal conversation instead of four.
A real local agent when it matters
Licensed agents at our Camp Hill, PA office, licensed in PA, TX, VA, MD, OH, TN, and KY. When you have a claim, we help you contact the carrier and answer adjuster requests. English, Nepali, and Hindi spoken.
Whether you run a single Sprinter on expedited freight or a few vans on local courier routes, your policy has to match your work, your weight rating, and your contracts. Dragon quotes your van through Progressive Commercial and handles the federal filing when you run under your own authority.
Call for a quote on the spot. Online requests answered within 1 hour on business days.
Visit us: 1525 Cedar Cliff Dr STE 202, Camp Hill, PA 17011
Cargo, delivery, and Sprinter vans insured as commercial vans; common coverages and cost factors.
Coverages for courier businesses and why personal auto typically does not cover business use.
$300,000 filing for for-hire property carriers under 10,001 lbs; $750,000 at 10,001 lbs or more.
Who needs operating authority, and the private carrier, exempt commodity, and commercial zone exceptions.
Accepted equipment types, authority age, and insurance requirements for Relay carriers.
Sources checked November 2026.
Explore Related Coverage
Ready to compare carriers and get a quote?
Dragon Insurance is an independent agency in Camp Hill, PA. We shop 30+ carriers to find your best rate.
Prefer to talk it through?
Get a real quote from a licensed advisor. English, Nepali, and Hindi spoken.
About the Author
Bimal GurungCEO, Agency Principal & Licensed Insurance Agent
Bimal Gurung is CEO and Agency Principal of Dragon Insurance Services, an independent agency in Camp Hill, PA that compares 30+ carriers for clients across Pennsylvania, Texas, Virginia, Maryland, Ohio, Tennessee, and Kentucky.
Meet the Dragon Insurance teamContinue Reading
Business
New Authority Trucking Insurance for New MC Numbers
11 min read
Business
Commercial Van Insurance for Contractors
12 min read
Business
Box Truck Insurance Cost 2026: Pricing Guide
10 min read
Business
Motor Truck Cargo Insurance: Who Needs It in 2026
14 min read
Business
Commercial Auto Insurance Guide
13 min read