Home Insurance
Every part of your home, explained
Tap any dot to see exactly what coverage protects that part of your home.
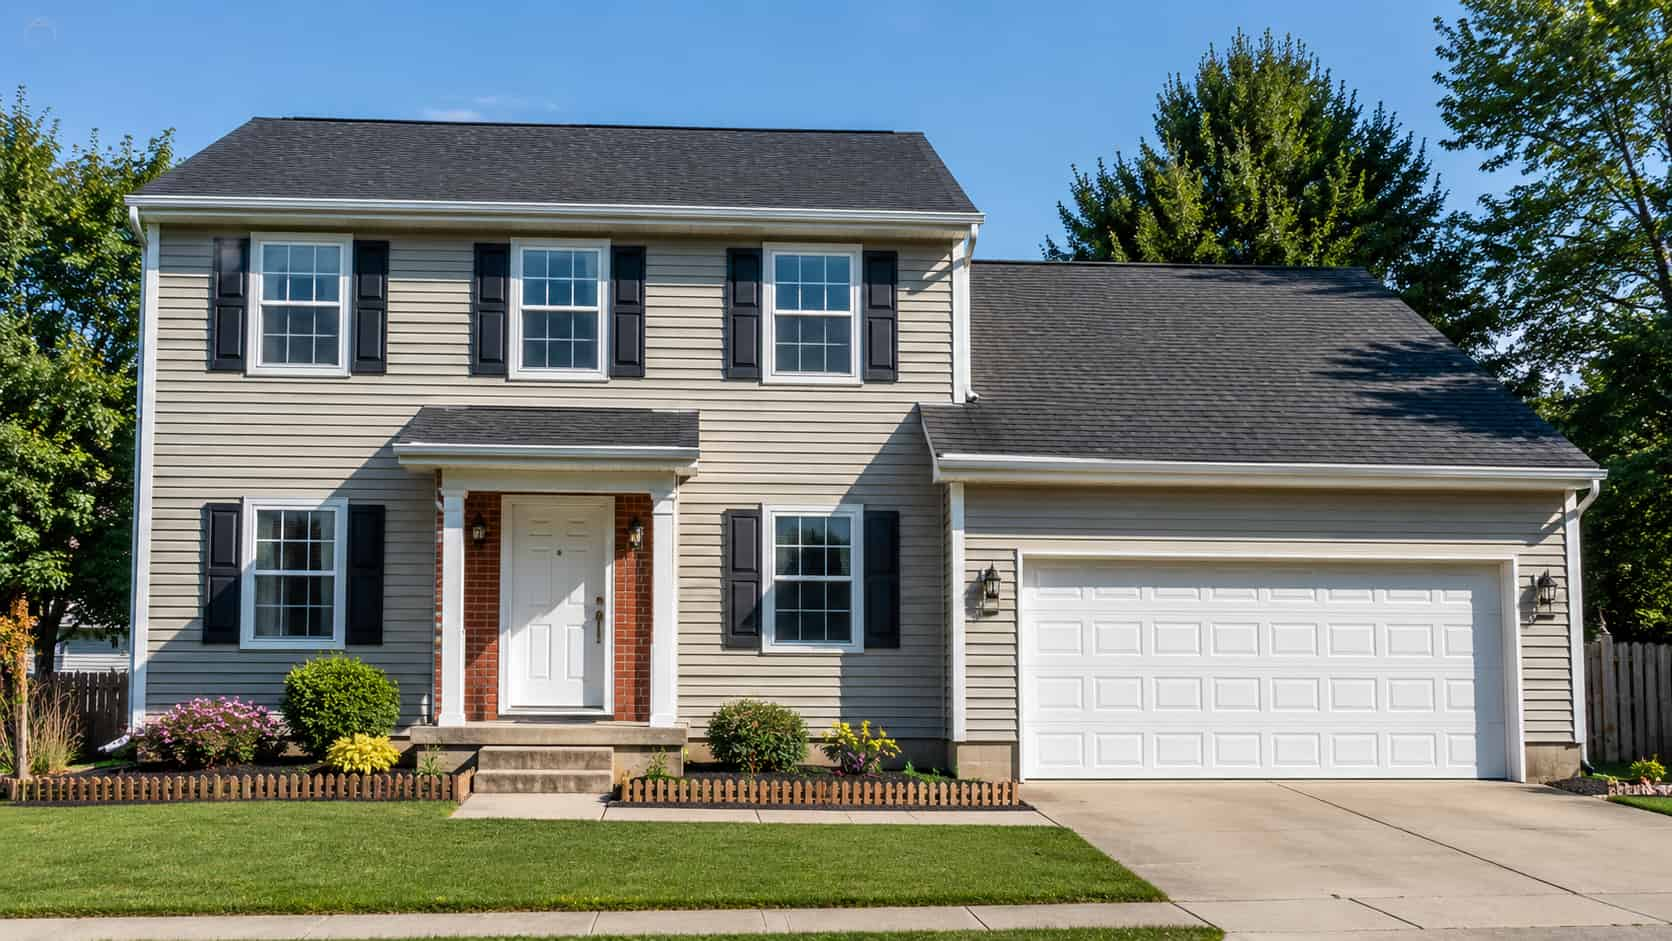
Tap any numbered dot to see what it covers
Ready to protect your home?
We compare 30+ carriers in one call. Local team, no call center.
Home Insurance for Harrisburg and Central PA Homeowners
Safeguard your home, belongings, and liability with a policy designed for your property and budget.
Licensed in PA, TX, VA, MD, OH, TN & KY only. Quotes available for these states.
Quick Answer
What It Covers
Dwelling (Coverage A)
Pays to repair or rebuild the structure after a covered loss such as fire, wind, hail, or a burst pipe. The limit should reflect current rebuild cost, not what you paid or what the home would sell for. Rebuild cost has risen faster than market value in recent years, which is why so many homes are now underinsured.
Personal Property (Coverage C)
Covers furniture, clothing, electronics, and household goods, usually set at 50 to 70 percent of the dwelling limit. Replacement cost settlement pays current prices while actual cash value deducts depreciation, and the difference on a total loss is often tens of thousands of dollars.
Personal Liability (Coverage E)
Pays legal defense and damages if you are found responsible for injuring someone or damaging their property, on or off your premises. Standard limits run $100,000 to $500,000, and anyone with meaningful savings, a pool, a trampoline, or a dog should look at an umbrella above it.
Additional Living Expense (Coverage D)
Pays the extra cost of living elsewhere while your home is being repaired: rent, meals above your normal grocery spend, storage, and pet boarding. After a serious fire this can run a year or more, so the limit matters.
Medical Payments (Coverage F)
Pays small medical bills for a guest injured on your property regardless of fault, which resolves minor incidents before they turn into liability claims.
Other Structures (Coverage B)
Covers detached garages, sheds, fences, and driveways, typically at 10 percent of the dwelling limit. Owners who add a large detached garage or workshop and never raise this limit are frequently short at claim time.
What It Does Not Cover
- Flood and surface water, which requires a separate NFIP or private flood policy
- Earthquake and earth movement, including sinkholes in most forms
- Wear and tear, rot, and deferred maintenance
- Pest, rodent, and termite damage
- Mold beyond a small capped amount on most policies
- Sewer and drain backup unless you add the endorsement
- Business property and business liability run from the home
- A home left vacant beyond the period stated in the policy
Why You Need It
Rebuild confidently after a loss
Home insurance protects your biggest investment: your home. It covers damage from events like fire, storms, theft, and more, while also protecting you from liability if someone is injured on your property. With the right coverage, you can recover quickly from unexpected losses without facing major financial hardship.
Coverage Options
Standard
First-time homeowners with straightforward needs.
- Dwelling + contents
- Base liability limits
- ALE
Enhanced
Homeowners with upgraded interiors or valuables.
- Higher dwelling limits
- Scheduled items
- Water backup
Premium
High-value homes needing broad protection.
- Guaranteed replacement
- Higher liability
- Loss assessment
Real Customers. Real Savings.
Sanj Thakur
“I couldn't be happier with the service I received from Bimal - Dragon Insurance.”
What You Will Need
- 1Year built and square footage
- 2Roof age and updates
- 3Current policy declarations
- 4Security system details
Watch how to get a quote online (35 sec)
What Impacts Your Rate
Roof age and material
The most decisive factor on a modern home quote. Many carriers will not write a roof over about 20 years old, and several now settle older roofs at actual cash value rather than replacement cost, which can leave an owner paying most of a roof replacement themselves.
Rebuild cost, not market value
Carriers rate on what it costs to rebuild, using square footage, finishes, and local labor and material costs. This is why a home can be worth less than it costs to insure, and why a purchase-price-based limit is usually wrong.
Protection class and location
Distance to a fire station and a hydrant sets your protection class, and local claim trends for wind, hail, and water losses adjust it further.
Credit-based insurance score
Permitted in Pennsylvania and most states Dragon serves, and it moves premium more than most homeowners expect. It is one of the reasons two neighbors in similar homes can be quoted very differently.
Claims history
Carriers pull roughly five to seven years of claims through the CLUE database, including claims filed by the previous owner on that address. Frequency matters more than size, and a pair of small water claims can affect eligibility more than one large fire.
Systems and safety features
Updated electrical, heating, and plumbing keep an older home insurable at standard rates. Monitored alarms, water leak detection, and automatic shutoff valves earn credits with several carriers.
Frequently Asked Questions
Replacement cost coverage helps rebuild your home without major out-of-pocket costs.
Flood coverage requires a separate policy.
Most homeowners choose higher limits to protect savings and assets.
Yes. Bundling usually lowers premiums and simplifies billing.
High-value items may need to be scheduled for full coverage.
Turnaround varies by property details and carrier requirements. We will confirm timing after we review the basics.
Yes. Other structures coverage can protect garages and sheds.
Claims can affect rates, but we compare carriers to minimize impacts.
Coverage C is personal property coverage. It pays to repair or replace your belongings (furniture, clothing, electronics, appliances) if they are damaged or destroyed by a covered peril such as fire, theft, or a windstorm. Standard HO-3 policies set Coverage C at 50 to 70 percent of your dwelling (Coverage A) limit. For a home insured at $300,000, that means $150,000 to $210,000 in personal property coverage. Replacement cost personal property coverage pays today's prices with no depreciation deduction; actual cash value pays the depreciated amount. Dragon Insurance recommends replacement cost on Coverage C for most homeowners.
Coverage E is personal liability coverage. It pays for bodily injury or property damage claims made against you when you or a household member are legally responsible. For example, if a guest slips on your icy walkway and sues, Coverage E pays for your legal defense and any judgment up to your policy limit. Standard limits run $100,000 to $500,000. If you have significant assets or own a pool, trampoline, or dog, higher limits or a personal umbrella policy are worth considering. Dragon Insurance helps homeowners choose an appropriate Coverage E limit based on their asset exposure.
Quote Support
Ready to compare carriers?
Submit your details and an advisor will reach out soon.
Prefer to talk now? Tap to call and we’ll guide you through the next steps.
Contact Us
Request a Quote or Consultation
Tell us a bit about what you need and we will respond as soon as possible.
Local Coverage
Home Insurance Agency Camp Hill PA
Dragon Insurance Services is an independent home insurance agency at our Camp Hill location at 1525 Cedar Cliff Dr STE 202, Camp Hill, PA 17011. We help homeowners in Camp Hill, Lemoyne, Harrisburg, Mechanicsburg, and throughout Cumberland County compare quotes from top-rated carriers. See our Camp Hill home insurance page for West Shore homes, or Arlington, TX home insurance for hail-country homeowners in Tarrant County.
Whether you need homeowners insurance in Camp Hill PA for a single-family home, a manufactured home, or a rental property, we shop 30 plus carriers to find replacement-cost coverage that fits your budget. Call us at 717-229-5115 or request a quote online and we typically respond within 1 hour on business days.
Locally based in Camp Hill, PA, serving clients across Pennsylvania, Texas, Virginia, Maryland, Ohio, Tennessee, and Kentucky.
Shopping around? Read Independent vs Captive Insurance Agent: Which Should You Use? to understand why comparing carriers matters before you buy. Thinking about Progressive? See how to get a Progressive home insurance quote and how it bundles with auto.
Blog
Home insurance articles
Home insurance guidance, coverage tips, and ways to save across PA, TX, VA, MD, OH, TN, and KY.
May 1, 2026
Homeowners Insurance Guide What It Covers, What It Costs, and How to Save
Two-thirds of U.S. homes are underinsured. Learn what an HO-3 covers, how RC vs. ACV can cost you thousands on a roof claim, and how PA homeowners compare to the national average.
Read article →
June 7, 2026
Best Home Insurance Companies 2026: Top Picks from Dragon Insurance
The best home insurance for 2026 depends on replacement cost coverage, claims service, and your state. Dragon shops Safeco/Liberty Mutual, Openly, Foremost, Plymouth Rock, and Westfield. Get a free quote to see rates for your state.
Read article →
October 3, 2026
Openly Home Insurance Review 2026: Who It Fits and How to Get a Quote
Openly is a premium home insurer you can only buy through an independent agent. Here is who it fits, what its HO-5 and landlord policies cover, and how Dragon quotes it side by side with our other home carriers.
Read article →
July 13, 2026
Why Are Home Insurance Rates Rising in 2026?
Home insurance rates are rising nationwide, with Virginia and Pennsylvania among the hardest hit. See what is really driving 2026 increases and the discount levers you control regardless of carrier.
Read article →
Explore Related Coverage
Auto Insurance
Bundle auto and home with us for a multi-policy discount.
Learn more
Umbrella Insurance
Extra liability protection above your home policy limits.
Learn more
Landlord Insurance
Specialized coverage if you rent out a property.
Learn more
Condo Insurance
HO-6 coverage for condo owners, fills the gap your HOA master policy leaves.
Learn more
Renters Insurance
Coverage for tenants, bundle with your next home purchase later.
Learn more
Manufactured Home Insurance
Mobile and manufactured home coverage, quoted with Foremost and other specialty carriers.
Learn more