Loading
Preparing your coverage insights...
Our Locations
Loading
Preparing your coverage insights...
A guide to commercial van insurance for trades and service businesses: when a personal policy stops covering a work van, employee drivers, tools and upfits, hired and non-owned auto, what drives the price, and liability minimums in PA, TX and VA.
Get a commercial van insurance quote. We quote your work vans with Progressive, biBerk, and National General side by side.
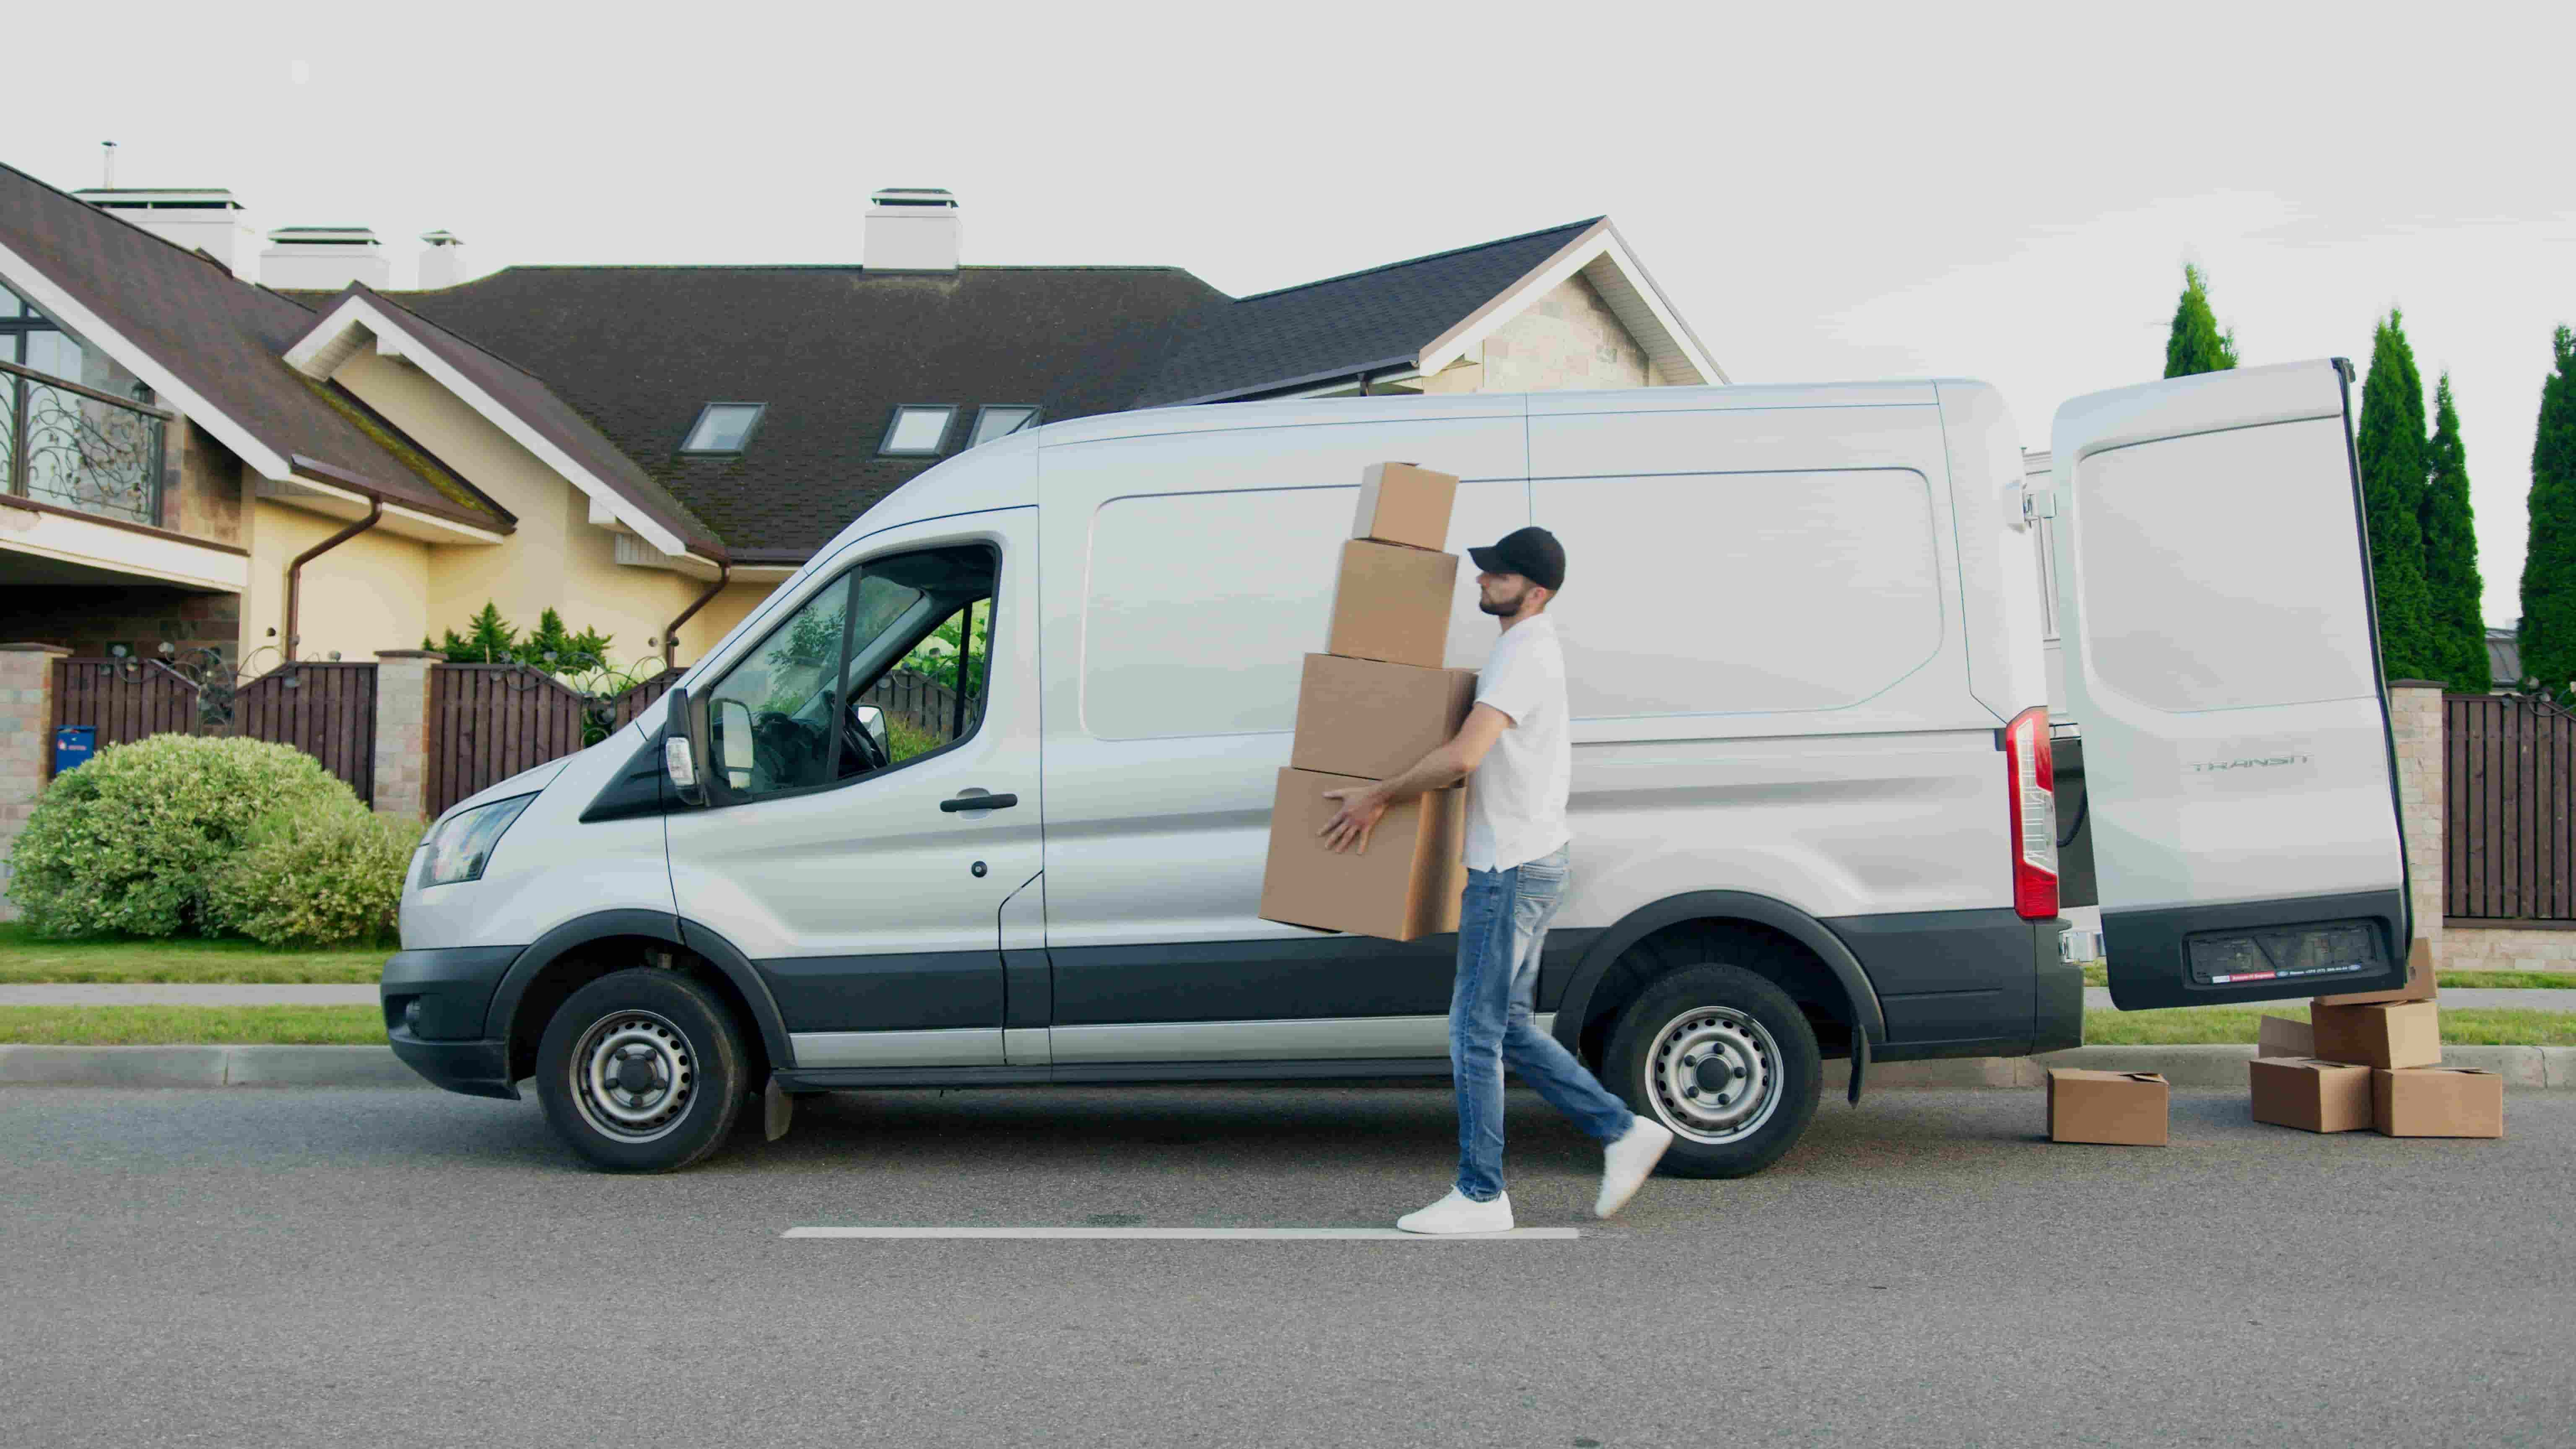
Your van is the shop. It carries the ladders, the pipe, the meters, the parts bins, and usually a second tech who is not you. When something goes wrong on the road or in a customer's driveway, three separate questions come up at once: is the van covered, is the driver covered, and are the tools inside covered?
Dragon Insurance is an independent agency in Camp Hill, PA that quotes work vans for plumbers, electricians, HVAC techs, cleaners, and landscapers. Below is how commercial van insurance answers each of those three questions, where the gaps usually sit, and what moves your price.
Quick Answer
What is commercial van insurance for contractors? It is a commercial auto policy written on your work vans, cargo vans, and pickups. It covers liability for crashes you cause, damage to the van, and permanently attached gear like ladder racks and shelving, and it can cover employees who drive for you. Loose tools need separate tools and equipment coverage. Dragon quotes contractor vans with Progressive, biBerk, and National General. Call 717-229-5115.
Key Takeaways
Any van, cargo van, or pickup that hauls your tools, carries your crew, or drives to paid jobs is a work vehicle, and it should be insured as one. This guide covers the light vehicles service businesses run every day, under 10,001 pounds gross vehicle weight rating (GVWR).
Running a box truck, dump truck, or anything heavier? That is quoted as commercial trucking insurance, which Dragon writes through Progressive, GEICO, and Trinity Underwriters.
A personal policy tolerates some business driving, but not a van that exists to do the job. According to the Insurance Information Institute, if a vehicle is used primarily in business, there is likely no coverage under a personal auto policy, and a vehicle owned by a business gets no coverage under one at all. For contractors, that line is crossed in three common ways.
For the full side-by-side on personal versus commercial coverage, limits, and how commercial auto works for every kind of business, read our commercial auto insurance guide. The rest of this post stays on the problems specific to trades and service vans.
Work Van on a Personal Policy?
Move it to a commercial policy before a claim forces the question.
We quote your van with Progressive, biBerk, and National General side by side, with your drivers listed, so you see the real price of covering the way you work.
Yes. A commercial auto policy can cover employees who drive your vans for work, as long as the carrier knows who they are. Progressive Commercial states that commercial auto insurance can cover your employees when they drive for work, and that you will usually list all drivers when you set up a policy. Here is how that plays out for a crew.
Take-home vans count as owned autos.The Insurance Information Institute notes that the business auto policy covers owned autos taken home by employees, which is how most service companies run on-call techs. One thing the van policy never pays is the injured employee's own medical bills and lost wages. Progressive Commercial points out you need workers' compensation for employee injuries, so we quote workers' compensation alongside the van policy and close that gap in the same call.
This is the gap contractors find most often, usually after a break-in. According to Progressive Commercial, van insurance does not cover loose tools, equipment, and other materials stored in your business vehicle. To protect them, it recommends inland marine coverage added to a general liability or business owners policy.
According to Insureon, small businesses typically pay an average of $48 per month for tools and equipment insurance. Dragon quotes tools coverage alongside your general liability policy with the business carriers we write, so the van, the tools, and the jobsite liability are priced together and a break-in does not fall between policies.
Equipment bolted to the van is treated as part of the van. Progressive Commercial states that standard commercial insurance for vans covers permanently attached gear, such as ladder racks and shelving units. The catch is making sure the claim pays what that build-out actually cost.
Most van claims touch more than one policy. Use this map to check that every piece of a typical service van loss has a home.
| What gets damaged or hurt | Policy that responds |
|---|---|
| Another driver's car and injuries | Commercial auto liability |
| Your van after a crash, theft, or storm | Commercial auto collision and comprehensive |
| Ladder racks and bolted-in shelving | Commercial auto physical damage, as part of the van |
| Loose tools and meters inside the van | Tools and equipment (inland marine) coverage |
| Equipment you are hauling to install | Installer's floater |
| Your injured employee | Workers' compensation |
| A crash in an employee's own car on a job | Hired and non-owned auto (HNOA) |
Estimators, supervisors, and new hires often drive personal cars to job sites, and your van policy does not follow them. Progressive Commercial describes non-owned auto insurance as extending liability coverage to your employees' vehicles when they are used occasionally for work.
HNOA is added to your commercial auto policy, or written on its own for a business with no company vehicles. Our commercial auto guide breaks down what HNOA does and does not cover.
Van, Tools, and Crew
Get the van, the tools, and your drivers quoted in one call.
We bundle commercial auto, tools coverage, general liability, and HNOA so a single break-in or crash does not land in the gap between policies.
Trades vans tend to cost more to insure than the average business vehicle. According to Insureon, small businesses pay an average of $245 per month for commercial auto insurance, while construction and installation contractors pay an average of $264 and $299 per month, respectively. Your own price comes down to a handful of factors.
Because each carrier weighs these factors differently, the same van and the same crew can price very differently from one carrier to the next. That spread is the reason to compare. Request a commercial van insurance quote and we shop Progressive, biBerk, and National General for you, or call 717-229-5115 for a price on your exact vans and drivers.
Every state sets a liability minimum, and a work van has to meet it, but the minimum is rarely enough for a contractor. Here is what three of the states we serve require for a standard vehicle.
Those numbers are a legal floor, not a business plan. The Insurance Information Institute notes that many insurers recommend a business auto limit of $1,000,000, with $500,000 as the minimum, and general contractors and commercial property managers often ask for proof of higher limits before you start work. We quote the limit your contracts call for in Pennsylvania, Texas, Virginia, Maryland, Ohio, Tennessee, and Kentucky, so the certificate you hand a client shows the limits they asked for.
Bring these to the first call and we can price your vans, drivers, and tools together with Progressive, biBerk, and National General side by side.
About Your Vans
About Your Drivers and Tools
Have this list in front of you. We start your quote on the call.
Call 717-229-5115Does commercial auto insurance cover employee drivers?
Yes. A commercial auto policy can cover employees who drive your company vans for work. Carriers usually ask you to list every regular driver and review each driver's motor vehicle record. Employee injuries are a workers' compensation claim, not an auto claim. We quote both so your crew is covered on the road and on the job.
Can I use personal auto insurance on my work van?
Usually not. The Insurance Information Institute says a vehicle used primarily for business likely has no coverage under a personal auto policy, and a vehicle owned by a business has none. If the van carries your tools to paid jobs most days, quote it on a commercial policy before a claim tests the personal one.
Does commercial van insurance cover tools stolen from the van?
No. Commercial van insurance covers the van and permanently attached gear, not loose tools and materials stored inside. A tools and equipment policy, also called inland marine, covers tools in the van, at the jobsite, or in storage. We quote it with your general liability so a break-in is a covered claim.
Are ladder racks and van shelving covered?
Generally yes, when they are permanently attached. Progressive Commercial states that standard commercial van insurance covers permanently attached gear such as ladder racks and shelving units. Declare the upfit when you quote and keep the invoices, so a total loss pays for the build-out, not just the bare van.
How much is commercial van insurance for a contractor?
It depends on your drivers, vehicles, location, and limits. According to Insureon, construction contractors pay an average of $264 per month for commercial auto insurance. For a price on your actual vans and crew, call 717-229-5115 and we compare Progressive, biBerk, and National General side by side.
What if my employees drive their own cars to jobs?
Add hired and non-owned auto (HNOA) coverage. It protects your business if an employee causes a crash in a personal car while working, and sits above the employee's own auto limits. It does not repair the employee's car. HNOA can be added to your commercial auto policy or quoted on its own.
What are the commercial van insurance requirements in Pennsylvania?
Pennsylvania requires at least $15,000/$30,000 bodily injury liability, $5,000 property damage liability, and $5,000 in medical benefits. Most contractors carry far more, because clients and general contractors often require higher limits on a certificate. Dragon quotes Pennsylvania work vans from our Camp Hill office.
One call, several carriers
We quote your work vans with Progressive, biBerk, and National General side by side, so you see the real lowest price instead of a single company's offer.
Fast, honest quoting
Call and we start your quote on the spot. Online requests get a reply from a licensed agent within 1 hour on business days.
Your whole business in one place
General liability, commercial auto, workers comp, and tools coverage placed and serviced by one agency, with one renewal conversation instead of four.
A real local agent when it matters
Licensed agents at our Camp Hill, PA office, licensed in PA, TX, VA, MD, OH, TN, and KY. When you have a claim, we help you contact the carrier and answer adjuster requests. English, Nepali, and Hindi spoken.
One van or a fleet of ten, Dragon quotes the van, the drivers, the tools, and the jobsite liability together with the carriers we write, then lays the options out side by side. One call. No pressure. English, Nepali, and Hindi spoken.
Call for a quote on the spot. Online requests answered within 1 hour on business days.
Visit us: 1525 Cedar Cliff Dr STE 202, Camp Hill, PA 17011
Personal auto gaps for business vehicles, employee drivers, and hired and non-owned auto.
Racks and shelving covered as part of the van; loose tools are not.
Average commercial auto premiums for small businesses and contractors.
Average tools and equipment premium and scheduling items over $2,500.
Pennsylvania minimum liability and medical benefits limits.
Sources checked October 2026.
Dragon Insurance Services LLC is a licensed independent insurance agency. This guide is general information as of October 2026 and is not legal advice. Coverage varies by carrier and policy, and all coverage is subject to policy terms and underwriting approval. Contact us for a personalized quote.
Explore Related Coverage
Ready to compare carriers and get a quote?
Dragon Insurance is an independent agency in Camp Hill, PA. We shop 30+ carriers to find your best rate.
Prefer to talk it through?
Get a real quote from a licensed advisor. English, Nepali, and Hindi spoken.
About the Author
Bimal GurungCEO, Agency Principal & Licensed Insurance Agent
Bimal Gurung is CEO and Agency Principal of Dragon Insurance Services, an independent agency in Camp Hill, PA that compares 30+ carriers for clients across Pennsylvania, Texas, Virginia, Maryland, Ohio, Tennessee, and Kentucky.
Meet the Dragon Insurance teamContinue Reading