Loading
Preparing your coverage insights...
Our Locations
Loading
Preparing your coverage insights...
Add an extra layer of liability protection beyond your auto and home limits.
Licensed in PA, TX, VA, MD, OH, TN & KY only. Quotes available for these states.
Quick Answer
Pays covered bodily injury claims from a serious at-fault accident once your auto policy's own liability limit is fully used.
Extends over your homeowners, condo, or renters liability coverage if a guest or visitor is seriously injured on your property.
Covers property damage you are legally responsible for once it exceeds your underlying auto or home policy's property damage limit.
Pays attorney fees and court costs to defend you against a covered liability lawsuit, even one that later turns out to be groundless.
Extends to certain claims your auto and home policies exclude entirely, including libel, slander, defamation, and false arrest.
Can cover certain personal injury offenses, such as invasion of privacy, that fall outside standard auto and home liability wording.
Protects you for covered liability incidents that happen anywhere in the world, not only in the states we serve.
Extends over your landlord policy if a tenant or their guest is seriously injured on a rental property you own.
Adds a higher liability limit above your boat or watercraft policy for a serious accident on the water.
Pays a covered judgment or settlement once the limit on your auto, home, or watercraft policy is fully exhausted, up to your umbrella limit.
In many states, an umbrella policy can add excess uninsured or underinsured motorist coverage above your auto policy's own UM/UIM limit, for injuries caused by a driver who carries too little insurance or none at all.
Extends the same liability protection to a spouse, children, and other relatives who live with you and are named on your underlying auto and home policies.
Can extend liability protection above the vehicle owner's or rental company's own policy if you cause a serious accident while driving a car that is not yours.
Why You Need It
A standard auto or home insurance policy caps your liability at a set dollar limit, and a single serious incident can produce a judgment well beyond that limit. Picture a serious at-fault auto accident where another driver is badly hurt, a dog bite that leaves a visitor with a lasting injury, or a social host liability claim after a gathering at your home where a guest is later involved in a drunk-driving accident. In any of these situations, your auto or homeowners policy pays up to its own liability limit, and if the judgment or settlement runs higher, the difference can come out of your savings, your home equity, or a garnishment of future wages. Legal defense costs alone can add up quickly even when a claim is eventually resolved in your favor, and those costs come out of your underlying policy's limit unless a broader umbrella policy is in place to absorb them separately. An umbrella policy sits above those underlying policies and picks up where they leave off, paying the remaining liability up to your umbrella's limit and covering legal defense costs along the way. It is one of the most affordable ways to protect assets you have spent years building, including a paid-off home, retirement savings, a college fund, or equity in a rental property, all of which can otherwise be reached by a large, unpaid judgment. Households with a teen driver, a rental property, a pool, or a dog often carry more everyday liability exposure than they realize, which is exactly the exposure an umbrella is built to sit above. As an independent agency, Dragon Insurance compares umbrella options across the carriers on our panel so you get a limit that matches your actual assets and household risk, not a one-size-fits-all number.
Households with a home, one or two vehicles, and moderate savings to protect, who want a meaningful liability cushion at the lowest entry cost.
Families with multiple vehicles, a teen driver, or a rental property who have outgrown a $1 million limit.
Households with a boat, RV, or higher income to protect, who want a wider cushion than the standard $1 million or $2 million tiers.
High-net-worth households or families with significant assets and income who have the most to lose in a large liability judgment.
Underlying policy limits
Carriers require minimum liability limits on your auto, home, and other policies before an umbrella will attach. Raising an underlying limit to meet that requirement can itself change your overall cost.
Number of underlying policies
Covering more policies under one umbrella, such as auto, home, and a rental property, can affect pricing. Placing all of them with carriers on the same panel often keeps the math simpler.
Driving records in the household
A driver with recent tickets or accidents raises the liability risk the umbrella carrier is taking on. This includes any newly licensed teen driver added to the household policy.
Number of vehicles and drivers
More vehicles and drivers on the household's auto policy generally mean a higher umbrella premium. Removing a vehicle no longer in use can lower it again.
Properties owned
Rental properties, vacation homes, and additional real estate all add to the liability the umbrella needs to cover. Each property's own liability limit is checked against the umbrella carrier's requirement.
Watercraft or recreational vehicles
Boats, jet skis, and RVs raise liability exposure and can change your rate. Larger or faster watercraft typically carry more liability risk than a small boat.
Claims history
Prior liability claims on your underlying policies can increase the umbrella premium or affect eligibility. A clean claims history over several years generally works in your favor.
Coverage limit selected
Moving from a $1 million to a $5 million umbrella increases the premium, though usually by less per dollar of coverage as the limit rises. Most households find the jump between tiers smaller than expected.
The right amount depends on your assets, your income, and how much liability exposure your household carries, not a single set number. A good starting point is enough coverage to protect your net worth, including home equity, savings, and future earnings, above what your auto and home liability limits already provide. Call us and we will walk through your specific assets and household risk to recommend a limit, rather than guessing.
Yes. The liability portion of a renters or homeowners policy is often too low to cover a serious injury claim on its own. An umbrella policy sits above that liability limit and picks up where it leaves off, so a single bad incident does not have to reach into your savings.
It can, once the rental property's own landlord liability policy meets the umbrella carrier's minimum limit requirement. If a tenant or their guest is seriously injured at a property you own, the umbrella extends above the landlord policy's liability limit. Tell us about any rental property when you request a quote so we can confirm it is properly covered.
Yes. A household umbrella policy generally covers everyone insured under your underlying auto policy, including a teen driver, for liability claims above your auto policy's own limit. Adding a new teen driver is actually a common reason families add or increase umbrella coverage, since a new driver raises the household's overall liability exposure.
Most umbrella carriers set minimum liability limits on your auto, home, boat, and rental property policies before they will issue a policy, and those minimums vary by carrier. As an independent agency, we check your current limits against what an umbrella carrier requires and can raise any that fall short at the same time we add the umbrella. See our excess liability vs umbrella insurance guide for typical underlying limit requirements.
Generally, no. A personal umbrella is built to sit above your personal auto, home, and watercraft liability, not liability arising from a business you own or operate. If you need higher liability limits for a business, ask us about a separate commercial umbrella or excess liability policy sized to that risk.
Your cost depends on your underlying auto and home limits, the number of vehicles, drivers, and properties in your household, and the coverage limit you choose. It is generally one of the least expensive ways to add a large amount of liability protection. Call us for an actual quote, or see our excess liability vs umbrella insurance guide for typical cost ranges by coverage tier.
Yes, in many cases. Beyond paying claims that exceed your underlying policy limits, many personal umbrella policies also extend to certain claims that standard auto and homeowners policies exclude entirely, such as libel, slander, defamation, false arrest, and some invasion of privacy claims. Coverage for these extensions varies by carrier, so confirm the details with your agent.
Most umbrella carriers want your home and auto policies placed with the same company that issues the umbrella, or want you to meet their own minimum underlying limits. As an independent agency, Dragon Insurance can often still place your umbrella policy with a separate carrier even when your home or auto insurance sits elsewhere. Call us to talk through your specific setup.
It can, once your boat or watercraft policy carries the liability limit the umbrella carrier requires. A serious accident on the water can produce a liability claim well beyond a standard marine policy's limit, and an umbrella extends above it the same way it does for auto and home liability.
Often, yes. Many personal umbrella policies pay for your legal defense on a covered claim even if the lawsuit is later dismissed or you are found not liable, since a defense obligation can exist independently of the final outcome. This is one of the most overlooked benefits of an umbrella policy, since legal costs on a serious claim can add up long before any judgment is ever decided.
Your underlying auto or home policy pays first, up to its own limit, and your umbrella then pays up to its own separate limit on top of that. If a judgment somehow exceeds the combined total of both limits, you would be personally responsible for the remaining balance, which is why choosing a limit that reasonably matches your assets and income matters. Call us to talk through a limit that fits your specific situation.
No. A single personal umbrella policy sits above all of your underlying auto, home, rental property, and watercraft policies at once, as long as each one is scheduled on the umbrella and meets the carrier's minimum limit requirement. You do not need to buy a separate umbrella for each asset. Tell us about every vehicle, property, and watercraft you own so we can make sure all of them are properly scheduled under one policy.
Quote Support
Submit your details and an advisor will reach out soon.
Prefer to talk now? Tap to call and we’ll guide you through the next steps.
Contact Us
Tell us a bit about what you need and we will respond as soon as possible.
Local Coverage
Dragon Insurance Services is a licensed independent insurance agency at 1525 Cedar Cliff Dr STE 202, Camp Hill, PA 17011. We help households across Camp Hill, Lemoyne, Harrisburg, Enola, and Cumberland County add umbrella liability coverage from 30 plus carriers starting around $200 per year.
If you own rental property, have a pool, or want stronger asset protection above your auto and home limits, an umbrella policy is the most cost-effective way to get it. Call 717-229-5115 or get a quote online.
Locally based in Camp Hill, PA serving clients across Pennsylvania, Texas, Virginia, Maryland, Ohio, Tennessee, and Kentucky.
Blog
Learn how umbrella insurance works with your auto and home policies to protect your assets.
June 19, 2026
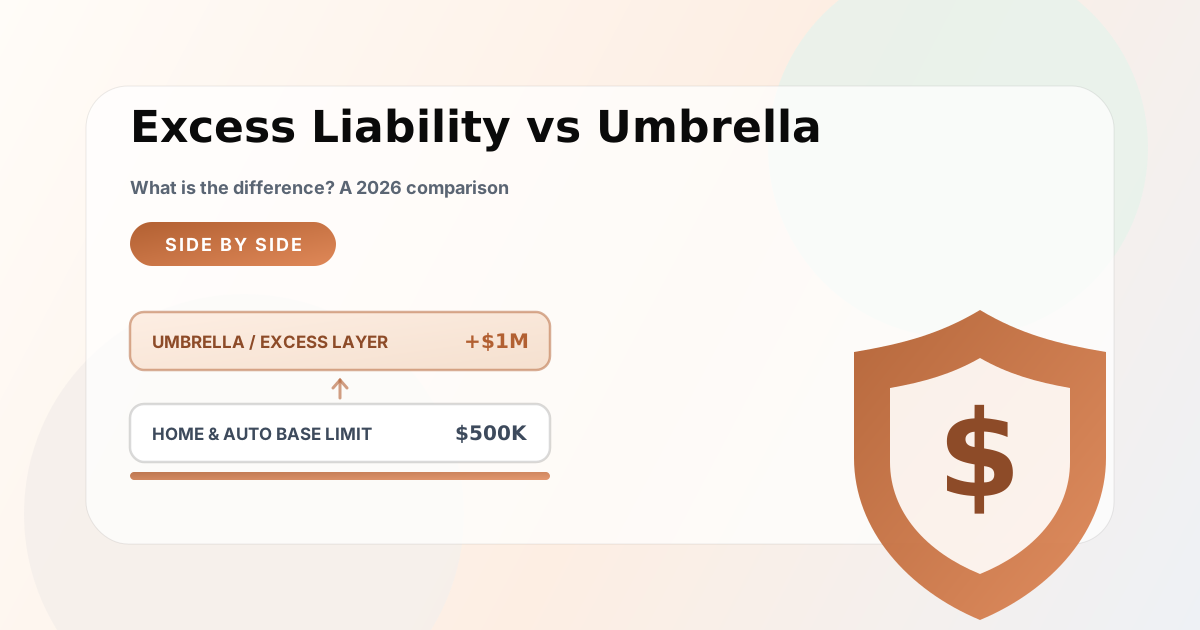
Excess Liability vs Umbrella Insurance: What Is the Difference?
Excess liability and umbrella insurance both add limits above your base policy, but umbrella can also cover claims your base policy excludes. Dragon places both through Safeco, Liberty Mutual, AAA, and Foremost.
Read article →
June 7, 2026
Best Home Insurance Companies 2026: Top Picks from Dragon Insurance
The best home insurance for 2026 depends on replacement cost coverage, claims service, and your state. Dragon shops Safeco/Liberty Mutual, Openly, Foremost, Plymouth Rock, and Westfield. Get a free quote to see rates for your state.
Read article →
May 1, 2026
Homeowners Insurance Guide What It Covers, What It Costs, and How to Save
Two-thirds of U.S. homes are underinsured. Learn what an HO-3 covers, how RC vs. ACV can cost you thousands on a roof claim, and how PA homeowners compare to the national average.
Read article →