
Loading
Preparing your coverage insights...
Our Locations
Loading
Preparing your coverage insights...
Laredo, TX
Dragon Insurance is an independent agency licensed in Texas, placing primary liability, motor truck cargo, physical damage, and non-trucking liability for owner-operators and small fleets based in Laredo and Webb County. We compare Progressive, GEICO, and Trinity Underwriters, plus specialty and excess and surplus markets through master brokerage relationships for new authority and harder-to-place risk. Call and we start same day for most standard risk.
Call for a quote on the spot. Online requests answered within 1 hour on business days.
Quick Answer
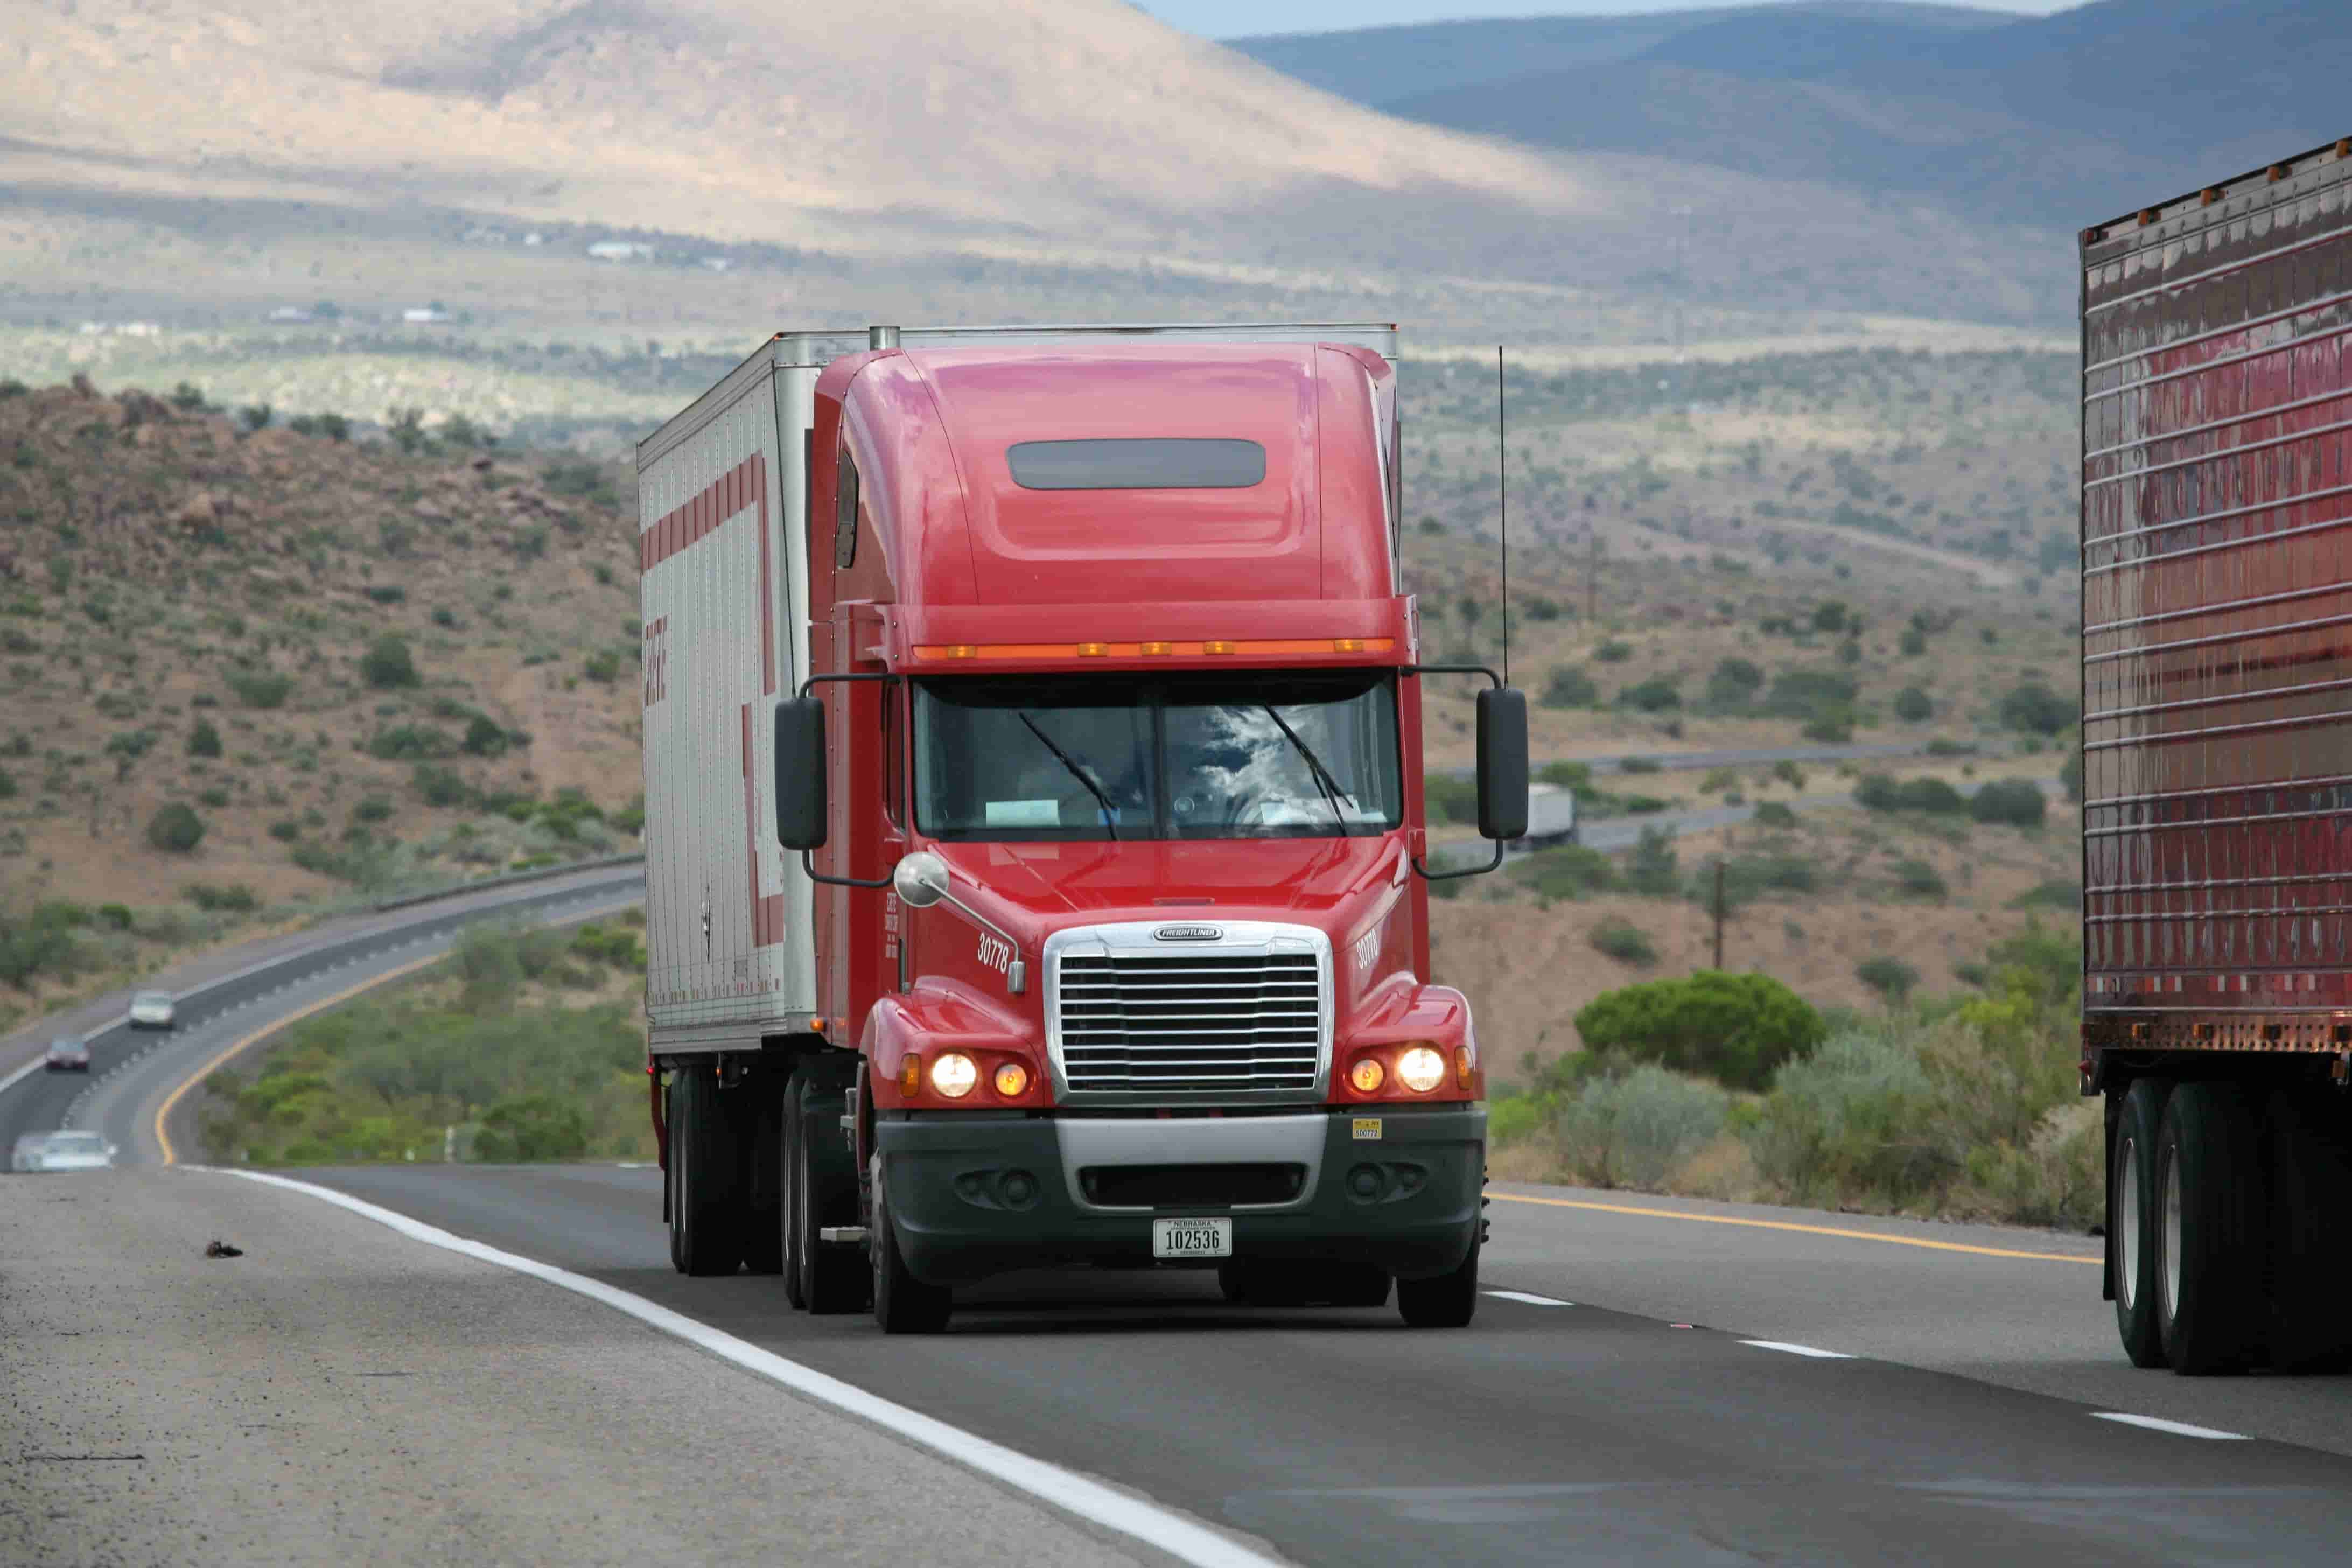
No US city has a freight identity like Laredo's. Port Laredo handled $353.94 billion in international trade in 2025, more than any other land port in the Western Hemisphere, and the Texas Comptroller counted over 3 million truck crossings through the port in 2024, roughly 62 percent of all trade moving across the Texas border with Mexico. Four international bridges connect the city to Nuevo Laredo, and two of them, the World Trade Bridge and the Colombia Solidarity Bridge, carry commercial truck traffic. Laredo is also where I-35 begins, so freight leaving your yard can run unbroken to San Antonio, Dallas, Kansas City, and the Upper Midwest.
That concentration changes how your policy should be built. A tractor turning eight short drayage moves a day between a bridge and a transload warehouse carries a different frequency profile than a long-haul unit, and cargo theft exposure on this corridor is a live underwriting factor rather than a talking point. We quote the radius, cargo limits, and deductibles against the operation you actually run, then place the coverage instead of handing you a report about it.
We are licensed in Texas and serve owner-operators and small fleets across Laredo and Webb County entirely by phone and online, with no office visit required.
Need the filing rules for every state you run through? Read our trucking insurance requirements by state guide.
New authority, placed correctly
MC authority under a year old has no loss history to price against, which closes most trucking markets. We place new Laredo authority through markets built for that segment, so you get bound and booking loads instead of declined.
Drayage and short-radius pricing understood
High-frequency bridge-to-warehouse turns underwrite differently than 1,200-mile lanes. We quote the radius you actually run so you are not paying long-haul pricing on a 50-mile operation.
The Mexico coverage gap, explained up front
Standard US commercial auto forms exclude Mexico from the coverage territory. We show you exactly where your US policy stops, and we place the US-side liability, cargo, physical damage, and non-trucking liability your Laredo units need.
Cargo terms compared, not defaulted
Texas ranks among the top three states for cargo theft. We compare cargo limits, deductibles, and theft terms across markets so a stolen trailer does not turn into an uncovered loss.
80+ five-star reviews
Real clients across Texas and the six other states we serve who called back after their first renewal.
Ready to compare trucking insurance quotes for your Laredo operation?
See the full commercial trucking coverage breakdown on our main commercial trucking page, or read the Texas commercial trucking insurance guide for statewide authority and filing rules.
Which rule applies to your Laredo truck depends on whether the freight crosses a state line. A tractor that picks up at the World Trade Bridge and delivers in San Antonio is intrastate and answers to TxDMV. The same tractor running that load to Oklahoma City is interstate and answers to FMCSA. Confirm which one you are before assuming either filing covers you, because the wrong filing leaves you unable to book loads.
| Authority type | Regulator | Primary liability minimum |
|---|---|---|
| Interstate (MC authority, crosses state lines) | FMCSA, 49 CFR Part 387 | $750,000 general freight; $1,000,000 or $5,000,000 for hazardous materials depending on the commodity |
| Intrastate (Texas only, TxDMV Number) | Texas DMV Motor Carrier Division | $500,000 for most carriers operating over 26,000 lbs |
| Intrastate household goods carrier under 26,000 lbs | Texas DMV Motor Carrier Division | $300,000 liability, plus cargo of $5,000 per vehicle and $10,000 aggregate |
These are legal minimums, not coverage recommendations. Neither figure includes cargo or physical damage coverage for general freight, which nearly every lender and shipper requires separately. Call us to confirm which authority type applies to your operation.
Dragon Insurance places trucking coverage for owner-operators and small fleets across Laredo and Webb County, including drayage operators working the World Trade Bridge and Colombia Solidarity Bridge, transload and warehouse fleets along the Mines Road and Killam Industrial corridor, and long-haul carriers running north on I-35 toward San Antonio, Austin, and Dallas.
See our Laredo, TX location page for our full range of coverage, or read the trucking requirements by state guide for how Texas compares to the other states we serve.
Questions Laredo owner-operators and fleet owners ask us most often.
It depends on your authority type. Interstate carriers hauling general freight north on I-35 need FMCSA-compliant primary liability of at least $750,000 under 49 CFR Part 387, with higher limits for hazardous materials. Carriers running only inside Texas need a TxDMV Number instead, and the state sets its own minimum of $500,000 for most carriers operating over 26,000 pounds. Almost every Laredo operation also needs motor truck cargo and physical damage coverage, which no statutory minimum requires but which every lender, broker, and warehouse contract on this corridor does. We quote all of it together so you are not left holding a filing that satisfies the state but fails your shipper.
Our primary trucking markets are Progressive, GEICO, and Trinity Underwriters, plus specialty and excess and surplus markets through master brokerage relationships for new authority, drayage fleets, and harder-to-place equipment. There is no single best carrier for every truck in Webb County. We compare the markets that actually write your radius, cargo, and authority age, then place the policy that gives you the coverage you need at the lowest premium those markets will offer.
Premiums can start around $200 a month for a clean-record truck with established authority, but the range runs into the thousands depending on your equipment, cargo, radius, authority age, and driving history. A tractor doing short-radius drayage between the World Trade Bridge and a Laredo transload yard prices very differently than a unit running 1,200-mile lanes up I-35. Call us with your equipment list and radius and we quote your actual operation rather than a corridor average.
Yes, with the right market. Authority under a year old has no loss history to price against, which is an automatic decline at many trucking insurers no matter how clean your driving record is. We place new-authority Laredo operators through markets that specifically underwrite that segment, submit the filing, and get you legal to book loads instead of sending you a decline letter.
Generally no, and this is the most misunderstood exposure on the Laredo corridor. Standard US commercial auto forms define the coverage territory as the United States, its territories and possessions, Puerto Rico, and Canada. Mexico sits outside that definition, and Mexican law only recognizes liability coverage issued by an insurer admitted in Mexico, so a US policy is not accepted as proof of financial responsibility south of the border. Dragon quotes and places the US side of your program: primary liability, motor truck cargo, physical damage, and non-trucking liability on your Laredo-based units. If your trucks physically cross rather than handing off to a Mexican carrier at the bridge, get written confirmation of where your US coverage stops before the tractor rolls, because a border loss on an unprotected unit is not something any policy fixes afterward.
Non-trucking liability covers your truck when you are off dispatch, driving it for personal use or deadheading outside your motor carrier's authority, which is exactly when the carrier's primary liability policy typically does not respond. Leased owner-operators running under someone else's authority out of Laredo need this specifically. We quote it alongside your primary liability so there is no uncovered window between loads.
It affects how underwriters read your operation. Port Laredo recorded more than 3 million truck crossings in 2024 and $353.94 billion in trade in 2025, and that density means short-radius drayage, bridge congestion, and cargo theft exposure all show up in pricing. Verisk CargoNet ranks Texas among the top three states for cargo theft, with national losses reaching an estimated $725 million in 2025. None of that makes a Laredo truck uninsurable. It means the cargo limit, deductible, and theft terms on your policy deserve real attention, and we compare those terms across markets rather than defaulting you into the cheapest cargo form.
Call 717-229-5115 and we start the same day for most standard risk. Intrastate carriers need a Form E filed electronically by the insurer through the Texas Motor Carrier Credentialing System before TxDMV will grant the certificate, so that filing is on us, not on you. Have your MC or DOT number, equipment list, radius of operation, and loss runs ready and we can usually quote accurately on the first call.
Sources
Laredo, TX
Dragon Insurance compares Progressive, GEICO, and Trinity Underwriters, plus specialty markets, for owner-operators and small fleets across Laredo and Webb County. New authority, drayage fleets, and specialty equipment welcome.
80+ five-star reviews · Independent agency, licensed in Texas
Blog
More guidance for Texas owner-operators and small fleets.
June 9, 2026
Commercial Trucking Insurance Requirements by State 2026
FMCSA requires $750,000 minimum liability for general freight, $1,000,000 for oil transport, and $5,000,000 for hazmat. Dragon helps owner-operators meet federal and state filing requirements in PA, TX, VA, MD, OH, TN, and KY.
Read article →
July 13, 2026
Owner-Operator Truck Insurance: The Complete Coverage Guide
Owner-operator truck insurance depends on one question first: are you leased to a motor carrier, or running under your own FMCSA authority? Dragon is appointed with Progressive, GEICO, and Trinity Underwriters to build the correct stack, primary liability, cargo, physical damage, NTL, and occupational accident, for either setup.
Read article →
June 9, 2026
What Is Non-Trucking Liability Insurance? Guide for Owner-Operators
Non-trucking liability (NTL) insurance protects owner-operators when they use their truck for personal, non-business purposes between loads. It is not the same as bobtail insurance. Dragon is appointed with Progressive, GEICO, and Trinity Underwriters for NTL coverage.
Read article →